
The gap between volume and revenue
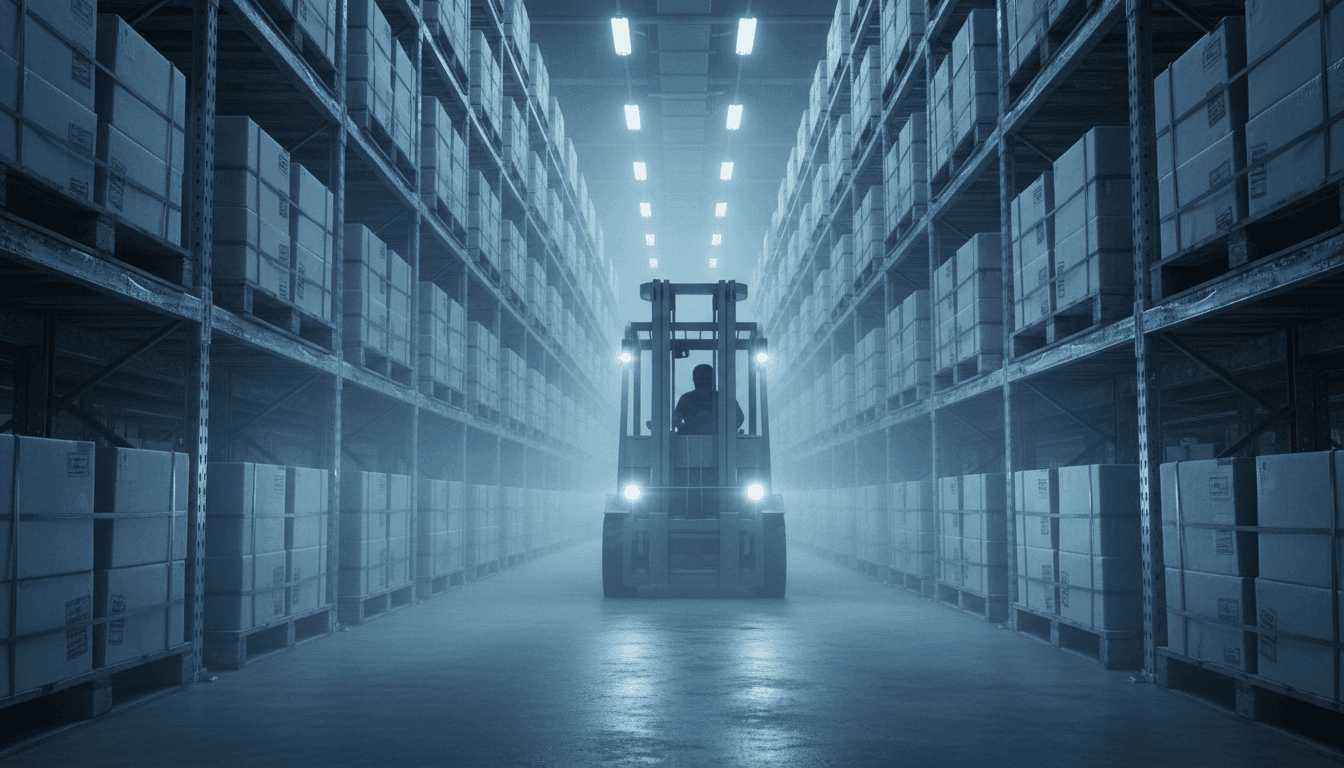
China's food cold-chain sector set a record in the first half of 2026: total demand reached 2 billion tonnes, up 4.7% year on year, as consumers bought more fresh produce, dairy and frozen goods and e-commerce platforms pushed same-day delivery deeper into lower-tier cities 1. On the surface, that looks like a straightforward growth story. It is not. Combined revenue for cold-chain logistics service providers rose only 3.7% to 290.18 billion yuan over the same period, according to data released by the China Federation of Logistics and Purchasing (CFLP) on August 16 1 2. Volume outgrew revenue by a full percentage point, which means the average price charged per tonne moved is quietly falling. For an industry that spent the past five years building capacity ahead of demand, that gap is the real story: China now has more cold-chain capacity chasing each tonne of freight, and pricing power is eroding for anyone who cannot differentiate on service or scale.
Who is absorbing the squeeze
The pain is not evenly distributed. China's cold-storage base is still dominated by thousands of small, regionally licensed operators running older, energy-inefficient facilities — refrigeration plants that were often built a decade ago to a much lower technical bar than today's standard. Industry research published in May frames 2026 as the year the sector pivots from simply having capacity to having good capacity, with newer national standards, tighter energy-efficiency expectations and stronger traceability requirements raising the operating cost of running a cold warehouse at all 6. Operators that already run older, higher-energy-draw depots face a choice: spend capital they may not have to upgrade refrigeration, insulation and monitoring systems, or keep operating on thinner margins as tonnage keeps arriving but rate cards do not keep pace. That dynamic explains why aggregate revenue growth trailed volume growth even in a demand environment that, by any historical measure, was strong.
The consolidation playbook: JD, SF Holding and foreign capital
At the other end of the market, scaled logistics platforms are pulling away, and their numbers make the bifurcation explicit. JD Logistics, whose network underpins the coldest links in China's grocery and pharmaceutical e-commerce, reported integrated supply-chain revenue of 59.4 billion yuan for the first half of 2026, up 18.5% year on year, with adjusted operating profit up 39.9% — roughly five times the cold-chain industry's overall revenue growth rate 5. SF Holding, which runs one of China's largest temperature-controlled networks alongside its express business, posted 8.2% year-on-year growth in its supply chain and international segment in the first quarter, more than double the sector average 4. Both companies are winning by bundling cold storage with automation, data visibility and integrated fulfilment rather than selling bare warehouse space or truck capacity — the exact capabilities that are hardest for fragmented regional players to replicate.
Foreign capital is reading the same signal. In March, MEDLOG — the logistics arm of shipping group MSC — and China Master Logistics (CMLOG) opened an 80,000-tonne, 24,000-square-metre cold storage facility in Shanghai's Lingang free trade zone, the third and largest site in a five-facility joint venture spanning Shanghai, Tianjin and Ningbo 3. The project is explicitly built to shorten the link between bonded import warehousing and cross-border cold-chain shipping, wiring itself into the premium end of the market — imported meat, dairy and seafood — where price sensitivity is lower and volumes are more predictable than in domestic last-mile grocery delivery.
Beijing's quality push accelerates the sorting
The policy backdrop reinforces rather than offsets this divide. Analysts tracking the sector describe 2026 as a transition from raw capacity growth toward standardization and consolidation, with new cold-storage construction expected to meet stricter national specifications and existing operators facing rising pressure to modernize or exit segments they can no longer run profitably 6. A separate industry read frames the shift as cold chain moving from a cost center that shippers tolerate to a value hub that they pay a premium for — but only for operators that can prove temperature integrity, traceability and speed with data, not just a working freezer 7. That is a bar low-capital regional operators will struggle to clear, and it is precisely the bar JD Logistics, SF Holding and the MEDLOG-CMLOG joint venture are built around.
The investment read
For investors, the H1 data is less a demand story than a market-structure story. Aggregate cold-chain growth headlines will keep looking healthy through 2026 because underlying consumption of fresh and frozen goods in China is not slowing. But the revenue-per-tonne compression embedded in the CFLP numbers suggests the sector's economics are increasingly won or lost at the operator level, not the industry level. Capital is likely to keep concentrating in listed logistics platforms with integrated tech stacks and in joint ventures backed by global shipping and cold-chain specialists, while thousands of undercapitalized regional cold-storage operators face a slow, standards-driven squeeze. Watch third-quarter CFLP data for whether the volume-revenue gap widens further — that would confirm consolidation is accelerating rather than stabilizing.
- [1]从田间到餐桌 上半年冷链“热“起来了 — China News Service (chinanews.com.cn), 2026-08-16
- [2]China's cold-chain logistics sector expands in H1 as demand grows: CFLP — Global Times, 2026-08-17
- [3]MSC's logistics arm expands cold chain network in China with five-facility joint venture — Container Mag, 2026-03-15
- [4]顺丰控股全球化战略提速 2026年一季度供应链及国际业务收入增长约8.2% — Sina Finance, 2026-04-29
- [5]JD.com Announces Second Quarter and Interim 2026 Results — GlobeNewswire / JD.com Investor Relations, 2026-08-13
- [6]2026中国冷链物流行业:从'有没有'到'好不好'的关键跨越 — China Research and Intelligence Network (chinairn.com), 2026-05-06
- [7]冷链物流:从'成本中心'跃升为'价值枢纽' — Sina Finance, 2026-05-08

 View certificate