
The so-what
South Korea's central bank spent three years doing nothing to its policy rate. It has now moved twice in six weeks. On August 27, the Bank of Korea (BOK) raised its base rate a quarter point to 3.00 percent, the second straight increase after July's move ended a 14-month freeze 1 6. Four days later, President Lee Jae-myung told the public that forecasters see the rate climbing to 3.5 percent by the first quarter of next year — a level the BOK itself has not committed to — and Korean bond yields moved on it 1. For investors in Korean rates, property, and the won, the interesting story isn't the 25 basis points. It's that Korea's semiconductor windfall has become a monetary-policy problem, and the country's central bank and its president are now sending investors two different signals about how far this goes.
A second hike in six weeks, not the last
The BOK's Monetary Policy Board voted 6-1 to raise the base rate to 3.00 percent, the highest level since January 2025, and lifted its 2026 growth forecast to 3.3 percent from 2.6 percent and its 2027 forecast to 2.9 percent from 2.1 percent 4 6. Governor Hyun Song Shin was explicit that the board wants to pause and assess rather than keep tightening on autopilot, saying the bank expects further increases to be gradual because it needs to weigh the impact of two hikes in a row and anticipates markets expecting a slower pace after this pre-emptive move 2 7. That is a governor trying to buy time. Inflation is still running above the BOK's 2 percent target, exports and domestic demand are both running hotter than expected, and the board flagged rising Seoul-area housing prices and an accelerating buildup in household debt as reasons it could not wait 1 5. Household debt crossed 2,000 trillion won (roughly $1.5 trillion) in the second quarter for the first time on record, and mortgage rates have climbed toward 8 percent even as the base rate sits at 3 percent — a gap that says Korean banks are already pricing in more tightening than the BOK has delivered 3.
The bonus economy behind Seoul's housing market
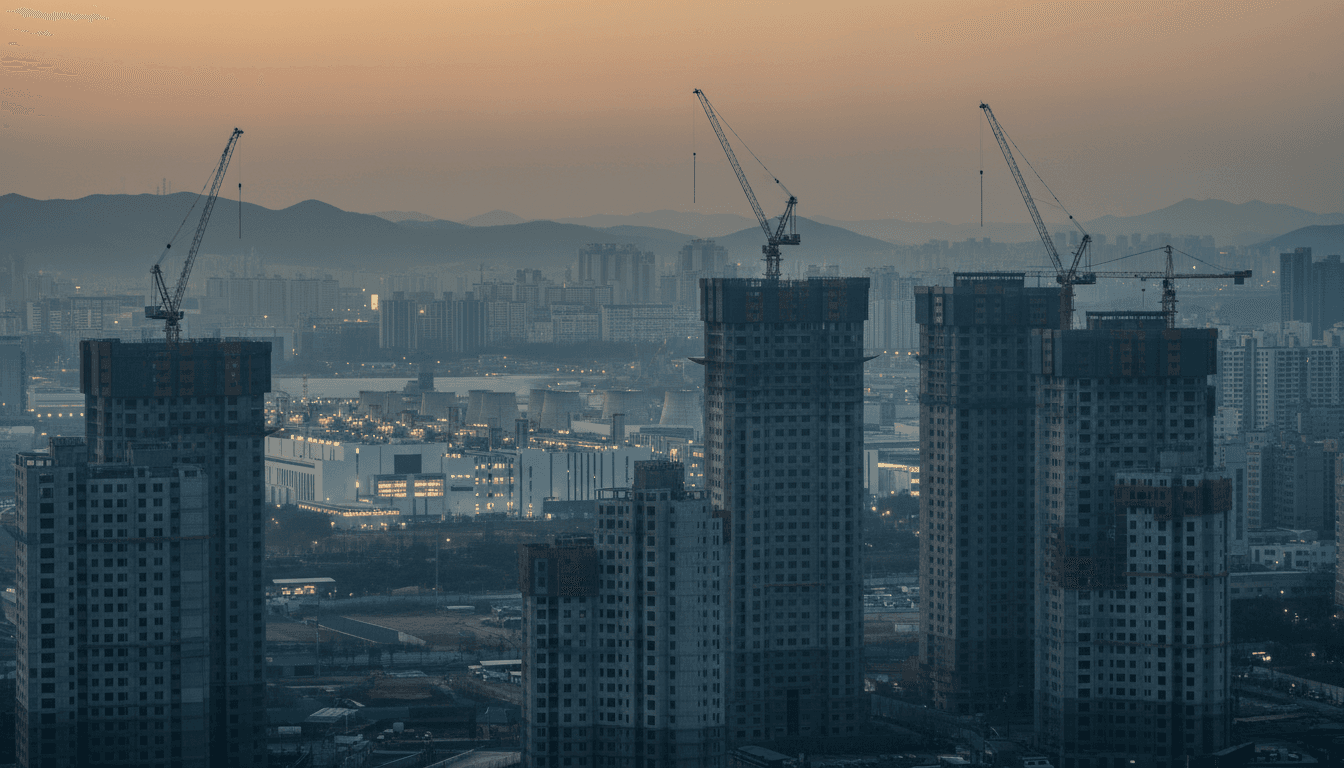
What makes this cycle different from a standard inflation fight is where the demand pressure is coming from. Samsung Electronics and SK Hynix are sitting on record memory and AI-chip profits, and both companies have built cash-bonus schemes that pay out a share of divisional operating profit directly to employees. SK Hynix set aside 10 percent of operating profit for bonuses, with individual payouts reportedly exceeding 1 billion won (about $662,000) for some staff, and the combined bonus pool at the two chipmakers is projected to grow from roughly 4 trillion won in 2026 to 16 trillion won in 2027 and 30 trillion won by 2028 8. That money has gone straight into real estate near the companies' fabs and employee shuttle-bus routes — so-called shuttle-zone apartments in cities like Dongtan and Giheung — where prices are now outrunning the broader Seoul metropolitan market. An 84-square-metre unit at a Dongtan Station complex sold for a record 2.08 billion won in May, beating a record set just a month earlier 8. Samsung has layered subsidized credit on top of the bonuses: starting September 1 it is offering employees without homes interest-free loans of up to 500 million won at 1.5 percent annual interest, while SK Hynix has widened its own mortgage program to cover all married staff up to 200 million won 8. In other words, two export champions are underwriting a regional housing boom that the central bank now has to lean against with blunt, economy-wide rate tools.
A president weighs in, and bonds move
The BOK has spent this cycle trying to look independent and cautious at once, which is what made President Lee's August 31 remarks notable. Lee did not call for a rate hike — the presidency has generally preferred lower rates given growth concerns and the government's own debt-servicing costs — but by telling would-be property speculators that a 3.5 percent rate by the first quarter of 2027 was a live forecast, he effectively did the BOK's tightening talk for it, and Korean bond yields responded 1. That is an awkward position for Shin: a governor who just told markets to expect a gradual pace now has the head of state publicly entertaining a faster one, for reasons that sound more like housing-market discipline than classical inflation targeting. Board minutes already show the committee was internally divided on the size and timing of the August move before it happened 9.
What to watch
Three things matter for positioning here. First, Korean government bond yields — the 10-year has room to keep drifting higher if the market prices in the president's 3.5 percent path rather than the governor's gradual one, which is a headwind for duration-sensitive Korean fixed income. Second, Samsung and SK Hynix themselves: their bonus schemes are now a visible input into national housing policy, which raises the odds of targeted mortgage or loan-to-value curbs aimed specifically at chip-belt districts rather than blanket rate hikes — a tail risk worth pricing for anyone holding Korean bank or property-adjacent equities. Third, the won: a hawkish BOK narrowing the rate gap with the Fed is currency-supportive, but only if growth holds up at the 3.3 percent pace the bank just underwrote. If chip export momentum cools before household debt does, Korea ends up with the tightening and none of the growth cushion that justified it.
- [1]President Flags 3.5% Rate Path, Rattling Korea's Bond Market — Seoul Economic Daily, 2026-08-31
- [2]Markets Cheer BOK's Back-to-Back Hike as Shin Signals a Dovish Path — Bloomingbit, 2026-08-28
- [3]Korean Mortgage Rates Near 8% as Household Debt Tops 2,000 Trillion Won — Seoul Economic Daily, 2026-08-28
- [4]BOK Raises Key Rate for 2nd Consecutive Session to 3%, Revises Up 2026 Forecast to 3.3% — The Korea Herald, 2026-08-27
- [5]BOK Faces Rate Dilemma Amid Stronger Growth, Record Household Debt — The Korea Times, 2026-08-25
- [6]Bank of Korea Delivers Back-to-Back Rate Hikes as Core Inflation Stays Elevated — CNBC, 2026-08-27
- [7]Bank of Korea Raises Rate to 3% to Get Ahead of Prices, Home Costs — Seoul Economic Daily, 2026-08-28
- [8]Samsung, SK Hynix Bonus Money Drives 'Shuttle Zone' Housing Boom — Seoul Economic Daily, 2026-04-17
- [9]Bank of Korea Board Divided as August Rate Hike Odds Rise — Seoul Economic Daily, 2026-08-06



 View certificate